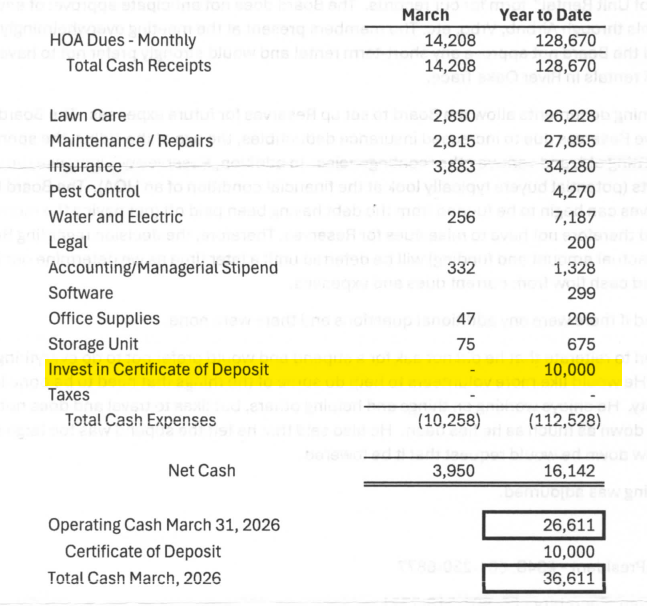
This post was originally supposed to be about another facet of our Board’s fee collection practice; however, I thought it more important to relate to you some things which I have recently learned. Look at Exhibit 1 below, particularly the entry highlighted in yellow. Exhibit 1 is a snapshot of the finance report given in the Minutes of our Annual Meeting held in March this year. This entry immediately prompted a question in my mind–“Where did we get ten thousand extra dollars to invest in a certificate of deposit (CD)”? This money would be tied up for several months and unavailable to spend on expenses until the CD matured. It is clear that this money was excess and the Board considered it a good idea to invest it.
Today I learned that we have paid our entire year’s premium for the insurance policy that we have with Auto-Owner’s Insurance. Our policy is handled through Park Avenue Insurance and I confirmed with their office that we paid the whole year’s premium in the amount of $44,043.90. I found this intriguing and again had to ask myself where we found $44,000 with which to make such a payment. Again, as above, the answer must be fee overcharges going back, at least, to the beginning of 2025. Now, the Board may argue that we accumulated the money due to fewer maint/repair projects than usual. This argument holds for short periods of time like 2-3 months; but, when we accumulate money for a year and longer, we may properly call that money excess–beyond the scope of normal operation–and that money should be refunded to members or credited to their accounts.
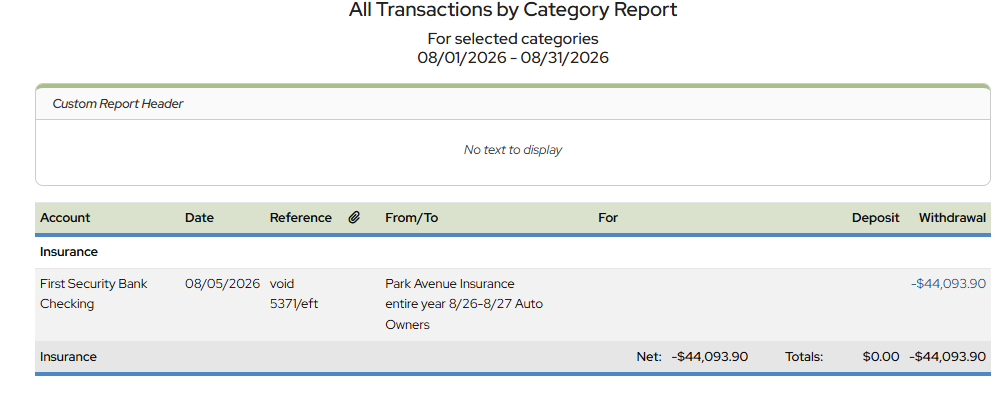
It is extraordinary, to say the least, that we have accrued so much money, over $50,000.00, especially to be paid in such a manner as an entire year’s insurance premium.
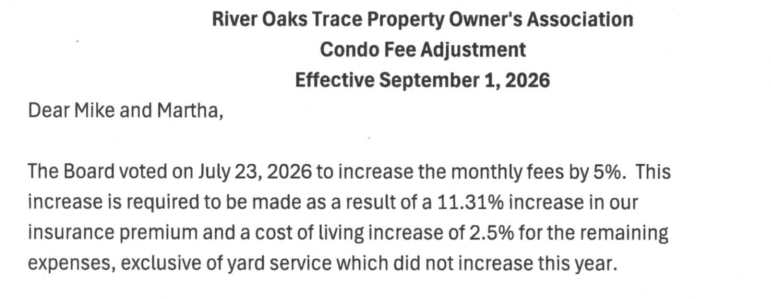
Exhibit 3 is an excerpt from the letter we received recently advising of our most recent fee increase of 5% to go into effect on 1 September. Read the excerpt above carefully and let it sink in. Are we to believe that we need higher fees due to an increased insurance premium now that we have paid our insurance premium for all of the year? Remember, we paid our premium using excess money collected over many months. That liability is now behind us and we will be collecting about $4,000 of revenue per month which would normally have been used to pay our premium–if we were paying it monthly. If, of course, the Board plans to pre-pay future premiums, this money will have to be set aside each month towards that purpose. Given similar circumstances, we will still be overpaying our fees going forward just like we have been for the past 18 months. Perhaps I am just too stupid to understand why we need a fee increase at this time and, perhaps, many of us also don’t understand why.
For the benefit of those of us who can’t comprehend the necessity of the latest fee upgrade, I invite a Board member to come on this venue and present the rationale for it in more detail than is given in their letter–including the arithmetic. It would be greatly appreciated…mm